Form 8858 for US expats self-employed abroad
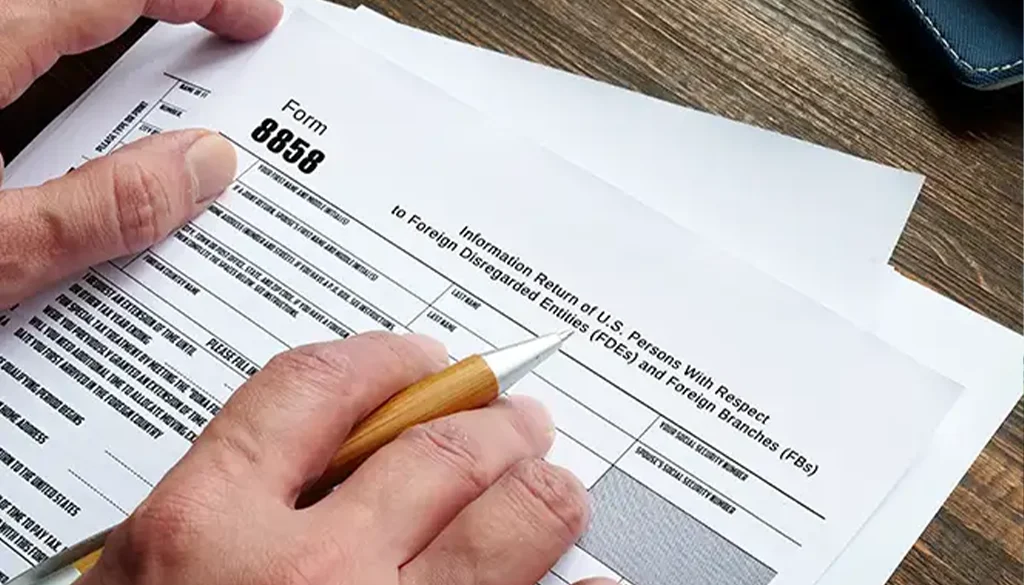
The Internal Revenue Service (IRS) requires US citizens with foreign business ownership or operations to submit Form 8858. This form, officially termed as the ‘Information Return of US Persons with Respect to Foreign Disregarded Entities (FDEs) and Foreign Branches (FBs)’ ensures tax compliance for US individuals involved in international self-employment.
The specifics of your situation will determine whether it’s necessary for you to fill out Form 8858. In case you have ownership over a Foreign Disregarded Entity (FDE) or if you’re managing a Foreign Branch (FB)—both are forms of foreign self-employment—Form 8858 becomes a requirement.
A Foreign Disregarded Entity or a Foreign Branch are legal entities or parts of legal entities that are distinct from you, the taxpayer, but are not taxed separately from their owners. The concept may appear complicated, but consider this: If you are a self-employed contractor in Spain, the firm that creates the money is different from you as a person, but it is not separate from you when it comes to paying taxes.

Rose-ann De Villa, an IRS Enrolled Agent and CPA with 15 years of expat tax experience, specializes in US tax preparation, tax planning, and tax advice for US citizens and Green Card holders living and working in the UK.
Rose-ann has been mentioned in the Daily Express UK news wherein she talked about Stimulus payments and Child Tax Credit refunds for US expats in the UK. *Schedule a consultation with Rose-ann today.
*30-minutes US$347.
Table of Contents
How do I know if I need to file Form 8858?
You may need to file Form 8858 if you are a US person who owns or operates a Foreign Disregarded Entity (FDE) or a Foreign Branch (FB). Simply providing services outside the United States does not automatically create a Form 8858 filing requirement. Instead, the requirement depends on how your overseas business is organized under the IRS rules.
What if I have two or more business activities?
Sarah is a finance blogger who also teaches yoga in the evenings and on weekends. Because the business activities are not the same, Sarah must file two 8858s, one for each.
David is a pool cleaner who also works as a contractor for a commercial swimming pool center during the weekdays. David cleans private pools on the weekends. Because the business activity is comparable, David can file one 8858.
Furthermore, Form 8858 isn’t limited to reporting a specific kind of income. Whether it’s income from sales, service charges, or otherwise, as long as it’s generated through your FDE or FB, it should be reported via Form 8858.
Foreign self-employment income
Foreign self-employment income generally refers to income earned from operating your own business or working as an independent contractor overseas. While many self-employed Americans abroad report this income on Schedule C, some may also need to file Form 8858 if their business qualifies as a foreign branch or foreign disregarded entity.
The following may be considered self-employment income:
- Profits from the sale of goods or services
- Earnings from freelance or consulting roles
- Rental income if you are actively involved in property management
Filling out Form 8858
Form 8858 requires detailed information about your foreign self-employment ventures. Starting with personal identification details like your name and tax identification number, the form covers a comprehensive range of information.
This includes:
- The name, address, and tax identification number of your foreign business entity or branch.
- Detailed financial information like income, deductions, and net profit or loss for your business or branch.
- Information about the assets and liabilities of the entity or branch.
- Details of transactions between the foreign disregarded entity or branch and its owners or related entities.
Can deductions or expenses related to foreign self-employment income be claimed on Form 8858?
Yes! Similar to domestically self-employed individuals, necessary and ordinary business expenses incurred in earning your self-employment income can be deducted, provided they are properly documented.
These expenses could include:
- Cost of goods sold
- Rent or lease expenses
- Salaries and wages paid to employees
- Professional fees such as legal or accounting services
- Depreciation and amortization of business assets
These expenses must be properly documented, and detailed records and receipts should be maintained in case of any future scrutiny by the IRS.
Given the complexities involved in Form 8858, it’s common for US expats to find it challenging. It’s important to understand not only US tax law but also the tax and business laws of the foreign country where the self-employment income is earned. If this sounds like a complicated task, don’t hesitate to consult a tax professional who specializes in international taxation.
Unique requirements of Form 8858
Form 8858 has some unique reporting requirements. For instance, you must report all transactions between yourself and your foreign entity or branch. This includes any monetary transactions or transfers of property. Furthermore, you’re required to report your foreign entity’s assets, income, liabilities, and equity, even if they’re not directly related to your self-employment income.
To calculate and report your net self-employment income on Form 8858:
- Determine your total business income.
- Calculate your necessary and ordinary business expenses.
- Subtract the total expenses from the total income to get your net self-employment income.
This net self-employment income should be reported on Form 8858 in US dollars, using the average exchange rate for the tax year.
Note: Form 8858 reports business information, while your taxable income is ultimately reported through your federal tax return and any applicable schedules.

Not sure if Form 8858 applies to you?
Multiple country income reporting
There is no minimum income threshold for filing Form 8858. Regardless of the amount of income, if you own a foreign disregarded entity or a branch of a foreign entity, you are required to file this form.
If you have self-employment income from different foreign countries, Form 8858 can be used to report all of them. However, a separate Form 8858 should be filed for each foreign entity or branch.
If you have income from multiple foreign countries, seeking advice from a tax professional can be beneficial. They can guide you through the intricacies, help you fulfill all reporting requirements, and potentially avoid penalties due to inaccurate or incomplete reporting.
Considerations for shareholders in Controlled Foreign Corporations (CFC)
If you’re a US expat with significant holdings in a CFC, you may need to comply with additional filing requirements and potentially face more tax liabilities. You may have to file Form 5471, ‘Information Return of US Persons With Respect to Certain Foreign Corporations’, especially if you own over 50% of the total value or combined voting power of the foreign corporation’s stock.
You can claim foreign tax credits or exclusions for your foreign self-employment income on Form 8858. The Foreign Earned Income Exclusion (FEIE) allows for a certain amount of your foreign-earned income to be excluded from US taxation. Meanwhile, the Foreign Tax Credit (FTC) can offset the taxes paid to foreign governments. These are reported on different forms, not directly on Form 8858, and they come with their own set of restrictions and limitations.
Filing specifics
When filing Form 8858, all amounts reported on US tax returns must be in US dollars. The IRS provides yearly average exchange rates, but in many cases, it’s appropriate to use the exchange rate prevailing when income was received, or expenses were paid.
Form 8858 should be filed alongside your federal tax return. Due to the complexities of international taxation, it’s important to ensure accuracy in reporting, as errors can trigger
audits or result in fines and penalties. Remember, the deadline for filing Form 8858 aligns with your individual or business income tax return’s due date. However, if you are a US citizen or resident living abroad, you may qualify for an automatic two-month extension.
Note: Beginning with the latest IRS instructions, certain parts of Form 8858 also require ISO 4217 currency codes when reporting functional currency information.
Consequences of non-compliance
The consequences of not filing Form 8858 when required can be severe. Non-compliance penalties begin at US$10,000 for each tax year, and if the information is not provided within 90 days after the IRS mails a notice, additional penalties can apply. Continuous failure to provide the necessary information can lead to even higher penalties.
Leveraging expertise: engage a tax professional
Because international tax law is complex and mistakes can result in substantial penalties, it’s often beneficial to seek assistance from a professional who specializes in US taxation for expats. They can guide you through the process of completing and filing Form 8858, assist in gathering necessary documentation, and provide advice to help you minimize your US tax liability while ensuring compliance with all US tax regulations.
Frequently Asked Questions
Can I file Form 8858 electronically?
Yes. If you file your federal tax return electronically, Form 8858 is generally submitted as part of that return when your tax software or tax professional supports the form. If you file a paper return, Form 8858 should be attached to your return before mailing it to the IRS.
Does filing Form 8858 mean I will owe more US tax?
Not necessarily. Form 8858 is primarily an information return used to report details about qualifying foreign branches and foreign disregarded entities. Whether you owe additional US tax depends on your overall tax situation, including your business income, available deductions, and whether you qualify for provisions such as the Foreign Earned Income Exclusion (Form 2555) or the Foreign Tax Credit (Form 1116).
Can I amend a tax return if I forgot to include Form 8858?
Yes. If you discover that Form 8858 should have been filed with a previously submitted return, you may be able to correct the omission by filing an amended return or following another IRS-approved procedure, depending on your circumstances. Because late-filed international information returns can carry significant penalties, it’s generally advisable to seek professional guidance before taking corrective action.
Do I need to keep records after filing Form 8858?
Yes. You should retain financial records that support the information reported on Form 8858, including income, expenses, assets, liabilities, and any transactions involving your foreign branch or foreign disregarded entity. Good recordkeeping can make it much easier to respond if the IRS requests additional information.
Can my business structure affect whether I need Form 8858?
Absolutely. The filing requirement depends largely on how your overseas business is organized. For example, operating as a foreign branch may have different reporting obligations than owning a foreign corporation or foreign partnership. If your business structure changes, your US international reporting requirements may change as well.
How can I determine whether my overseas business is a foreign branch or a foreign disregarded entity?
The distinction depends on how your business is legally organized and how it is treated for US tax purposes. While some businesses clearly fall into one category, others require a more detailed review of local law and IRS regulations. If you’re unsure, it’s worth confirming your business classification before filing your US tax return to avoid reporting errors.