Form 8858 for US expats with foreign rental income
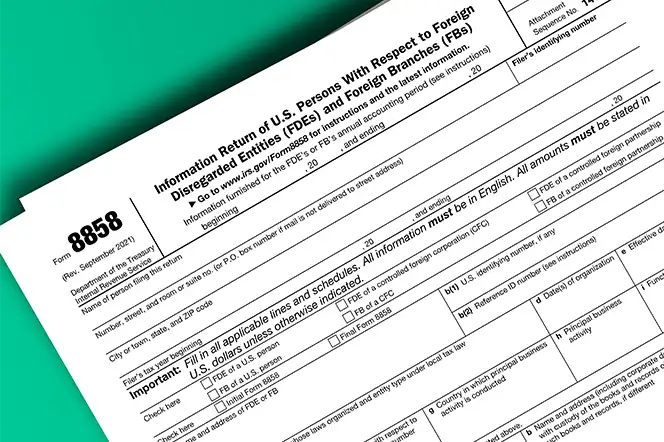
US expats with foreign rental property must file Form 8858 when the rental activity is treated as a Foreign Branch or conducted through a Foreign Disregarded Entity (FDE). This requirement can apply even when the property is owned directly in the taxpayer’s name.
IRS Form 8858 is used to report certain foreign business activities, including Foreign Disregarded Entities (FDEs) and Foreign Branches (FBs). An FDE is a foreign entity that is legally separate from its owner but disregarded for US tax purposes. A Foreign Branch, meanwhile, can include a foreign Qualified Business Unit (QBU), such as a separately identifiable foreign trade or business with its own books and records.

Rose-ann De Villa, an IRS Enrolled Agent and CPA with 15 years of expat tax experience, specializes in US tax preparation, tax planning, and tax advice for US citizens and Green Card holders living and working in the UK.
Rose-ann has been mentioned in the Daily Express UK news wherein she talked about Stimulus payments and Child Tax Credit refunds for US expats in the UK. *Schedule a consultation with Rose-ann today.
*30-minutes US$347.
Table of Contents
Am I required to submit Form 8858?
Yes. US taxpayers with foreign rental activity that constitutes a Foreign Branch or QBU must file Form 8858. The requirement can apply to rental property owned directly in your name as well as property held through a Foreign Disregarded Entity.
Why is my rental property considered a Qualified Business Unit (QBU)?
A Qualified Business Unit, or QBU, is generally a separate and identifiable part of a trade or business that maintains its own books and records.
For foreign rental property, this matters because a rental activity can be treated as a foreign QBU when it is operated as a trade or business and its financial activity is recorded separately from the taxpayer’s other finances.
Separate books and records can include:
- a dedicated rental spreadsheet
- a property-specific income and expense ledger
- bookkeeping software used for the rental
- separate records for rent, repairs, management fees, taxes, and other costs
Many landlords already keep this type of documentation to manage the property and prepare their local tax return.
If the foreign rental activity qualifies as a QBU or Foreign Branch, Form 8858 must be filed, even when the property is owned directly in the taxpayer’s own name.
Definition of rental income
Rental income generally includes any payment you receive for another person’s use or occupation of your property. The IRS defines rental income quite broadly. Basically, any funds you receive for the use or occupancy of property are regarded as rental income. This includes not only regular rent payments but also advance rent, expenses paid by a tenant, and the value of any services or property received instead of money.
If your tenant covers any of your costs, those payments are deemed rental income. For example, if a tenant pays the electricity bill for your rental property and deducts it from the usual rent payment, the IRS still regards this as rental income. You can then deduct these costs if they qualify as deductible expenses.
Additionally, Form 8858 requires information about the foreign rental activity, including:
- Gross rental income: This is the total amount you received from renting out your property, before deductions for expenses.
- Rental expenses: These are the costs you incur related to leasing out the property, such as upkeep, advertising, management fees, and even travel costs to visit the property.
- Net rental income: This is the gross rental income minus the permissible expenses.
As a US taxpayer, it’s imperative that you report your income in US dollars. Therefore, you need to convert your foreign rental income and expenses into US dollars using the correct yearly average exchange rate.
Foreign-currency amounts must also be translated into US dollars. The correct exchange rate can depend on the type of income, expense, asset, liability, or Form 8858 schedule being completed. It is therefore important to follow the instructions for each applicable form rather than automatically applying one yearly average rate to every amount.
Determining when to file Form 8858
You must file Form 8858 if you own a Foreign Disregarded Entity or operate a Foreign Branch or QBU that carries on the foreign rental activity. The requirement can also apply when the rental property is owned personally rather than through a separate foreign entity.
For example, a US taxpayer who owns and rents property in Italy may have a foreign rental QBU that must be reported on Form 8858. A separate Form 8858 requirement can also arise when the property is held through an FDE.
It’s also important to know that other foreign income is not treated the same as foreign rental income. Although it might appear that all income earned overseas would be grouped together, the IRS differentiates between different kinds of foreign income.
Here’s a quick rundown:
- Foreign earned income: Usually refers to wages, salaries, or professional fees for personal services rendered in a foreign country.
- Foreign passive income: Includes things like interest, dividends, rent, royalties, and annuities.
- Foreign rental income: This is a subset of foreign passive income, specifically from leasing property.
Foreign rental income is generally considered passive income unless the taxpayer provides substantial services or the activity falls under other special rules.
Getting assistance from a tax expert can be a godsend when ensuring you’re accurately reporting your foreign rental income and staying compliant with the IRS. They might even help you discover tax deductions or credits you didn’t know existed.

Stay compliant with your foreign rental income.
Deductions and expenses for foreign rental property
US taxpayers can generally deduct ordinary and necessary expenses connected with earning and maintaining foreign rental income. Similar to a US rental property, the IRS permits you to deduct certain expenses related to your foreign rental property. These often include:
- Property management fees
- Maintenance and repair expenses
- Property taxes
- Mortgage interest
- Insurance
- Advertising
- Professional fees
- Depreciation
- Qualifying travel expenses for rental-related tasks
However, there are specific rules or requirements for reporting these deductions on Form 8858.To claim these expenses, you need to itemize your deductions. Standard deductions won’t apply here. Also, bear in mind that any expenses you claim must be necessary for rental activities and should be reasonable in amount.
Furthermore, always keep records of your rental expenses. These may include:
- Receipts
- Invoices
- Bank statements
- Mortgage statements
- Property management records
- Local tax assessments
- Rental agreements
- Documents supporting the property’s purchase price and land value
Lastly, don’t forget the deduction for foreign taxes. If you pay income tax to a foreign country on your rental income, you might be able to claim a credit for these taxes on your US tax return. However, this can get complicated as it might involve other forms like Form 1116, so it’s best to seek professional advice.
Rental income reporting: Know the rules, avoid the trouble
Foreign rental income and expenses must be converted into US dollars. The appropriate exchange rate depends on the type of income, expense, asset, or liability being reported, so you should follow the instructions for the applicable form rather than use one exchange-rate method for every item.
Next, calculate your net rental income or loss:
- Determine your total reportable rental income.
- Calculate your allowable rental expenses.
- Subtract the allowable expenses from the rental income.
The result is your net rental income or loss, which is generally reported on Schedule E and also reported as required on Form 8858.
If you use the property for personal purposes or rent it below fair market value, special rules can apply. In these cases, the reporting and deduction rules may become more complex, particularly where a foreign entity or business operation is involved.
Other factors to keep in mind
If your foreign rental income comes from a Controlled Foreign Corporation (CFC), the IRS has a whole new set of rules. A Controlled Foreign Corporation, or CFC, is generally a foreign corporation that is more than 50% owned, by vote or value, by qualifying US shareholders after applying the relevant direct, indirect, and constructive ownership rules.
If you find yourself in this scenario, be aware of the Subpart F rules. These rules could tax the corporation’s income directly to the US shareholders, even if no distributions were made.
You may be able to claim the Foreign Tax Credit (FTC) for qualifying foreign income taxes paid on your rental income. Ordinary rental income generally does not qualify for the Foreign Earned Income Exclusion (FEIE), because the FEIE applies to income earned from personal services performed abroad. IRS
However, if you provide substantial services to tenants and part of the income is attributable to those services, different rules can apply.
Note: If you provide substantial services to tenants, such as services commonly associated with a hotel or similar business, the income may be classified differently. That could affect whether it is reported on Schedule E or Schedule C and whether self-employment tax applies.
E-Filing
The IRS now allows you to e-file Form 8858. Not only does this method save trees, but it also speeds up the processing of your return and, potentially, any refund you’re owed. However, keep in mind that if you’re filing Form 8858 separately from your tax return, you’ll need to send in a paper copy. The IRS only accepts separate filings of Form 8858 in this format.
- If your federal tax return is filed electronically and your tax software supports Form 8858, the form can generally be included with the electronic return.
- If you file a paper return, attach Form 8858 to the applicable return in accordance with the IRS filing instructions. Form 8858 is due on the same date as the return to which it is attached, including extensions.
There’s a lot to consider when dealing with Form 8858 and foreign rental income. While it’s crucial to understand all the intricacies involved, you don’t have to go at it alone. Consider bringing in a tax professional who’s experienced in expat taxation. They can ensure you meet your obligations correctly and do so in a way that’s most beneficial for you.
Frequently Asked Questions
Do I need Form 8858 if my foreign rental property is owned personally?
Yes. Owning foreign rental property directly in your own name requires Form 8858. Form 8858 also applies if you own a foreign disregarded entity or operate a qualifying foreign branch. The rental income itself is also reported on Schedule E.
Can I claim depreciation on a foreign rental property?
Yes. In many cases, foreign residential rental property can be depreciated for US tax purposes. However, the depreciation rules differ from those for US rental property, and the IRS generally requires foreign residential rental property to be depreciated under the Alternative Depreciation System (ADS). Since the calculation can be complex, it’s important to keep accurate records of your purchase price, improvements, and land value.
What exchange rate should I use for foreign rental income?
Foreign rental income and expenses must be converted into US dollars, but the appropriate exchange rate depends on the type of amount being reported. Some recurring income and expenses may use an average annual exchange rate, while other transactions may require the exchange rate in effect on the transaction date. Following the IRS instructions for the relevant tax forms will help ensure the correct method is used.
If my rental property makes a loss, do I still have to report it?
Generally, yes. A rental property that generates a loss may still need to be reported on your US tax return if you have a filing requirement. Whether you can deduct the full loss depends on several factors, including the passive activity loss rules, your income level, and how the property is used.
What records should I keep for a foreign rental property?
Good recordkeeping is essential. You should retain documents such as purchase records, rental agreements, bank statements, receipts for repairs and maintenance, mortgage statements, insurance records, foreign tax receipts, and depreciation schedules. Keeping complete records makes it easier to prepare an accurate tax return and respond to any future IRS questions.
What if I missed reporting my foreign rental income or forgot to file Form 8858?
If you discover that you should have reported foreign rental income or filed Form 8858 for a prior year, it’s usually best to address the issue as soon as possible. Depending on your circumstances, you may be able to correct the omission by filing an amended return or using an IRS compliance procedure. Because international reporting requirements can carry significant penalties, seeking advice from an experienced US expat tax professional is often the safest approach.