What is a T5 Slip?
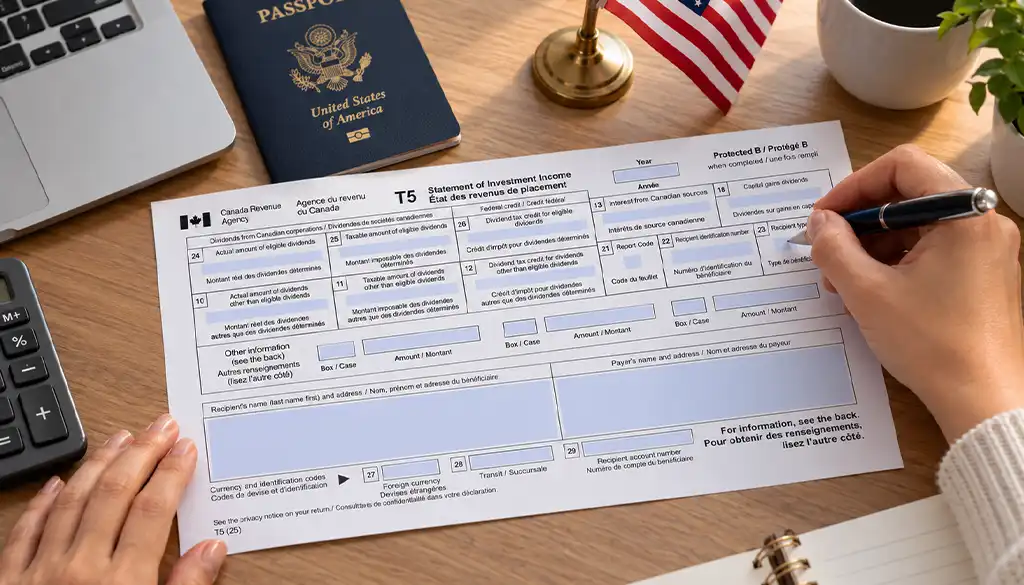
A T5 slip, officially called the Statement of Investment Income, is a Canadian tax document issued by financial institutions and other payers to report certain investment income to taxpayers and the Canada Revenue Agency (CRA). It helps taxpayers accurately report investment income on their Canadian income tax returns.
Deborshi Choudhury, an IRS Enrolled Agent with 18 years of expat tax experience, specializes in U.S. tax preparation, tax planning, and tax advice for U.S. citizens and Green Card holders living and working in the UAE and Canada. *Schedule a consultation with Deborshi today.
*30-minutes US$377.
Table of Contents
2025 tax year update (filed in 2026)
In January 2026, the Canada Revenue Agency (CRA) updated its electronic T5 filing specifications, introducing new validation requirements and changes to reporting fields. These technical updates primarily affect financial institutions and other T5 issuers rather than individual taxpayers.
Who receives a T5 slip?
Financial institutions and other investment-income payers generally issue T5 slips to Canadian residents who earn reportable investment income.
Typical recipients include individuals who have invested in:
- Interest-bearing savings accounts
- Term deposits
- Dividend-paying Canadian stocks
- Guaranteed investment certificates (GICs)
- Certain mutual funds or exchange-traded funds (ETFs) distributing investment income
- Corporate bonds and other interest-bearing securities
Businesses and other entities may also receive T5 slips.
Note: Mutual fund trusts generally issue T3 slips, while mutual fund corporations generally issue T5 slips. Check your fund’s structure to determine which slip applies.
For joint investment accounts, income is generally reported based on each person’s ownership and contributions, not an automatic 50/50 split. Family attribution rules may also affect who must report income from transferred or loaned funds.
What information is included on a T5 slip?
A T5 slip contains numbered boxes showing investment income, tax credits, and other details needed to complete a Canadian tax return.
T5 slip boxes and corresponding Canadian tax return lines
|
Box |
Information reported |
Canadian tax return |
|
10 |
Actual non-eligible Canadian dividends |
Included in Box 11 |
|
11 |
Taxable amount of non-eligible dividends |
Lines 12010 and 12000 |
|
12 |
Dividend tax credit for non-eligible dividends |
Line 40425 |
|
13 |
Interest from Canadian sources |
Line 12100 |
|
14 |
Other income from Canadian sources |
Generally line 12100 |
|
15 |
Foreign investment income |
Generally line 12100 |
|
16 |
Foreign tax paid |
Form T2209, line 40500 |
|
17 |
Canadian royalties |
Line 10400, 13500, or 12100 |
|
18 |
Capital gains dividends |
Schedule 3, line 17400 |
|
19 |
Accrued annuity income |
Line 11500 or 12100 |
|
24 |
Actual eligible Canadian dividends |
Included in Box 25 |
|
25 |
Taxable amount of eligible dividends |
Line 12000 |
|
26 |
Dividend tax credit for eligible dividends |
Line 40425 |
|
27 |
Foreign currency code |
Identifies the currency reported |
|
30 |
Equity-linked notes interest |
Line 12100 |
Canadian dividends are treated differently from ordinary interest income. Dividend gross-up rules increase the taxable amount reported, while the dividend tax credit may reduce the tax payable.
Do I need to report my T5 slip income on my tax return?
Yes. Canadian tax residents generally need to report taxable investment income shown on their T5 slips.
For example, if Box 13 shows CAD$500 in savings account interest, you would generally report that amount on line 12100 of your Canadian income tax return.
Certain GICs and other investment contracts may also require annual reporting of accrued interest, even when the interest has not yet been paid.
Do you have to report investment income under CAD$50?
Yes. Investment income is generally taxable even if no T5 slip is issued.
A payer generally does not need to issue a T5 slip if the total reportable amount paid or credited to one recipient during the year is below CAD$50. This threshold applies to the annual total, not each payment.
Investment income earned within Canadian TFSAs and RRSPs is generally not reported on personal T5 slips. However, US taxpayers may still have US tax or information-reporting obligations, depending on the account and applicable rules.

Expat US Tax is an expert in US-Canada taxation. Speak with our accountants today.
Can I get my T5 slip online?
Yes. You can access your T5 through your financial institution’s online banking platform or CRA My Account once the slip is available.
To find your 2025 T5 slip through CRA My Account:
Step 1: Sign in to CRA My Account. Visit the CRA sign-in page and complete any required identity verification. Once signed in, check for available T5 slips. Only slips received and processed by the CRA will appear. You may also be able to access your T5 slip through your financial institution’s online platform, if offered.
Step 2: Find your tax information slips. Open the Tax returns section and select Tax information slips (T4 and more). The exact menu labels may vary.
Step 3: Select the tax year. Choose 2025 to view available tax documents for that reporting year.
Step 4: Locate your T5 slip. Find T5 – Statement of Investment Income among the available documents and select the slip you want to review.
Step 5: Review your information. Check the reported income, recipient details, and tax year against your investment records. Save or print the document if that option is available. If your slip is missing or incorrect, contact the issuing institution. The CRA cannot display a slip until it receives the information from the issuer.
Important change for the 2026 filing season
The CRA no longer accepts telephone requests for paper copies of tax slips, including T5 slips. You can access available slips through CRA My Account or contact the issuing financial institution for a copy.
How do T5 issuers file information returns?
Financial institutions and other T5 issuers can file information returns electronically or on paper, depending on how many slips they submit.
Here’s a breakdown of both filing methods and their requirements:
1. Electronic filing. The CRA offers two electronic filing methods:
-
Web Forms: Allows issuers to submit up to 100 slips per submission, with automatic summary calculations.
-
Internet file transfer: Allows issuers to upload electronically prepared returns, including larger submissions.
The CRA’s 2026 technical specifications introduced account-number matching between slips and summaries, made the first recipient address line optional, and revised permitted characters in certain fields.
2. Paper filing. Issuers filing five or fewer T5 slips may generally submit paper returns. Those filing more than five slips must file electronically. A T5 information return includes the applicable T5 slips and a T5 Summary showing the amounts reported by the issuer.
What is the difference between a T5, T3, T4, and NR4 slip?
Canadian tax slips serve different reporting purposes. Identifying the correct form helps distinguish investment earnings from employment income, trust distributions, and payments to non-residents.
Differences between common Canadian tax information slips
|
Tax slip |
Official name |
What it reports |
|
T5 |
Statement of Investment Income |
Certain investment earnings |
|
T3 |
Statement of Trust Income Allocations and Designations |
Income and allocations from trusts |
|
T4 |
Statement of Remuneration Paid |
Employment income and payroll deductions |
|
NR4 |
Statement of Amounts Paid or Credited to Non-Residents of Canada |
Certain payments to non-residents and withholding taxes |
The appropriate form depends on the income source, investment structure, and recipient’s tax residency.
How does T5 income affect Americans living in Canada?
US citizens and Green Card holders generally must report Canadian investment income on their US tax returns, even while living in Canada.
For US tax purposes, dividends are reported using actual amounts (T5 Boxes 10 and 24), not Canada’s grossed-up amounts (Boxes 11 and 25). US qualified-dividend eligibility is determined separately, and income must be converted into US dollars. Learn more about how to report foreign dividend income.
Interest and dividends do not qualify for the Foreign Earned Income Exclusion (FEIE). However, Canadian income taxes paid or accrued may qualify for the Foreign Tax Credit through Form 1116, subject to limitations. T5 Box 16 reports foreign taxes withheld, not Canadian income tax paid, and should not automatically be claimed as a US credit.
Some Canadian mutual funds and exchange-traded funds (ETFs) may be classified as Passive Foreign Investment Companies (PFICs), potentially requiring Form 8621, depending on applicable exceptions.
Canadian registered accounts may also receive different US tax treatment and have separate reporting requirements.
Frequently Asked Questions
What if I have T5 slips from multiple sources?
If you hold investments with several financial institutions, you may receive more than one T5 slip. Report all applicable investment income from these slips on your Canadian tax return. Check each slip against your records to avoid omissions or double-counting income, particularly from jointly held accounts.
When should I receive my T5 slip for 2025?
Financial institutions generally had until March 2, 2026, to issue T5 slips for investment income earned in 2025.
The Canadian income tax filing deadline was April 30, 2026. However, self-employed taxpayers and those whose spouse or common-law partner was self-employed had until June 15, 2026, to file. Any taxes owed were generally due by April 30, 2026.
What happens if I forget to report T5 income?
The CRA may reassess your return and charge additional tax and interest on unpaid amounts. For 2025, a repeated failure-to-report-income penalty may apply if you omitted at least CAD$500 in 2025 and at least CAD$500 in any of the three preceding tax years. Other penalties may apply to deliberate or grossly negligent omissions.
If you’ve already filed, you can request an adjustment after receiving your notice of assessment.
Can I receive a T5 slip if I’m a non-resident of Canada?
T5 slips generally report investment income paid to Canadian residents. Certain Canadian-source payments made while you are a non-resident may instead be reported on an NR4 slip. If your Canadian residency changed during 2025, you could receive a T5 for income paid while you were a resident and an NR4 for qualifying payments received afterward. The applicable tax treatment depends on the income and any relevant tax treaty.
What if my T5 slip contains incorrect information?
Contact the financial institution that issued the slip and request a correction. The issuer must provide an amended T5 if the reported information needs to be changed. If you’ve already filed your tax return using incorrect amounts, you may need to request an adjustment after receiving your notice of assessment.
Can I file my Canadian tax return without a T5 slip?
Yes. If you cannot obtain your T5 before the filing deadline, use bank statements or other financial records to estimate your reportable investment income. For paper returns, include supporting statements and a note identifying the missing slip and issuer. If filing electronically, keep your supporting records in case the CRA requests them later.